Upward trend confirmed – new orders in the machine tool sector rise by 12 per cent in the second quarter
The recovery in the German machine tool industry is taking shape. In the second quarter of 2026, order intake rose by 12 per cent compared with the same period last year. Following a 15 per cent increase in the first quarter, this results in total growth of 14 per cent for the first half of the year. Domestic orders rose by 16 per cent, whilst orders from abroad increased by 13 per cent.
“Two consecutive quarters of double-digit growth in orders are an encouraging sign. We have passed the lowest point and the upward trend is taking hold,” says Bernhard Geis, Head of Economics and Statistics at the VDW (Association of German Machine Tool Manufacturers), commenting on the figures. “However, it is still too early to sound the all-clear. We are starting from a low base, and project business continues to make a significant contribution to growth. We can therefore only speak of a broad recovery in demand to a limited extent.”
Aviation and defence are driving demand
The trend continues to vary significantly across customer sectors. Aviation and defence are proving particularly dynamic. Demand from the electronics industry and medical technology is also viewed positively. The situation remains more challenging in metalworking and mechanical engineering. The greatest challenges continue to lie in the automotive and supplier industries. Their share of total sales in the German machine tool industry has fallen to 23 per cent by 2025. Mechanical engineering remains the largest customer, accounting for 27 per cent. By contrast, the aerospace industry has grown significantly: its share rose by five percentage points to 11 per cent within two years.
In the export sector, there are signs that the situation is stabilising
Improved order book has not yet reached production
The recovery has not yet reached the production sector. In the second quarter, production was estimated to be 6 per cent below the previous year’s level. In the first half of the year, production fell by a total of 7 per cent to around 5.9 billion euros. However, the improved order situation is likely to become increasingly evident in production as the year progresses. In the export sector, too, there are at least signs of stabilisation. In the second quarter, exports were still 4 per cent below the previous year’s level. This marks a significant slowdown in the rate of decline compared with the first quarter. The US, as the largest sales market, remains a key pillar of the sector. Deliveries to the US rose by 8 per cent in the first half of the year. By contrast, exports to China, the second-largest market, fell by 24 per cent. However, companies have recently reported a stabilisation and slight recovery in Chinese demand. In view of intense price competition, the ‘local for local’ principle is becoming increasingly important for German manufacturers with their own local production facilities. In Europe, German machine tool exports fell by 6 per cent overall in the first half of the year. France performed well, with an increase of 25 per cent, moving up to third place among the most important markets. Poland and the Czech Republic also provided positive impetus. India is likewise continuing its growth trajectory and is now the sector’s fourth-largest market.
Bernhard Geis, Head of Economics and Statistics at the VDW
Domestic orders are rising
The domestic market, however, remains under pressure. Domestic sales in the first half of the year were 10 per cent below the previous year’s figure. There are, however, positive signs from the rise in domestic orders. Currently, economic indicators such as the ifo Business Climate Index and the Purchasing Managers’ Index also point to improved sentiment in the industry. Imports fared better than domestic sales, falling by just two per cent. Japanese and South Korean manufacturers, in particular, were able to increase their sales in Germany. Overall, domestic consumption fell by 6 per cent, indicating that the slump in investment on the German market has not yet been overcome. Capacity utilisation has recently stabilised at around 75 per cent. At the same time, the structural adjustment process within the sector is continuing. In June, companies employed around 60,000 people – a good 6 per cent fewer than a year earlier. In real terms, production is now around a third below the peak levels of previous years. Bernhard Geis sums it up: “Overall order intake has now been moving in the right direction for half a year. The crucial thing now is for this to develop into a sustainable recovery.”
Background
The German machine tool industry is one of the five largest sectors within mechanical engineering. It supplies production technology for metalworking to all branches of industry and makes a significant contribution to innovation and productivity gains in industry. Owing to its absolutely key role in industrial production, its performance is an important indicator of the economic dynamism of the entire industrial sector. In 2025, the sector – with an average of around 64,500 employees (in companies with more than 50 staff) – produced machinery and services worth around 13.8 billion euros.
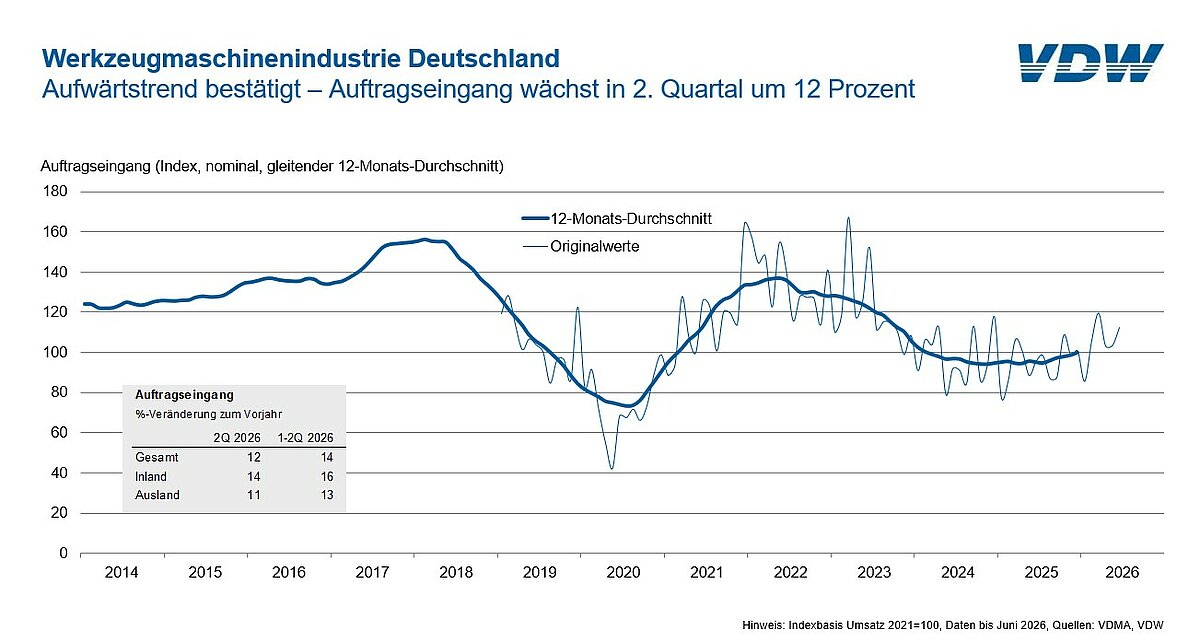
In the machine tool sector, the positive trend continued into the second quarter: new orders rose by 12 per cent compared with the previous year.
Source | Verein Deutscher Werkzeugmaschinenfabriken e.V.